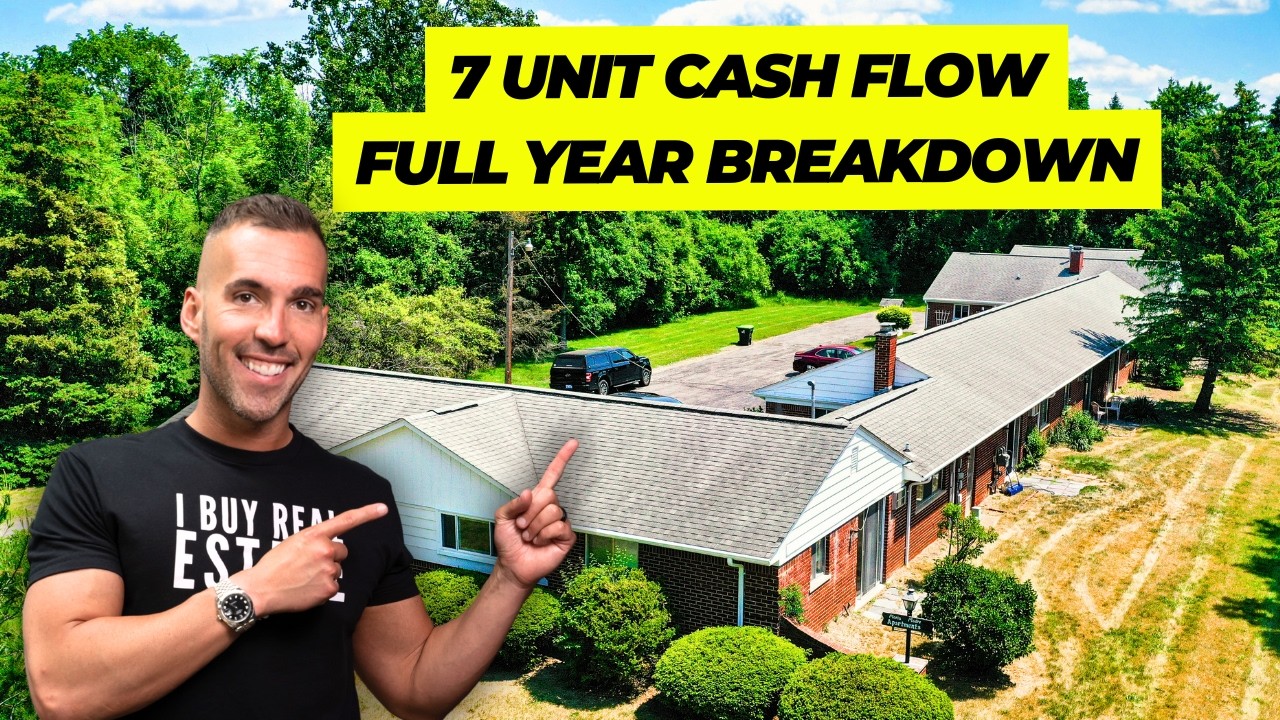
Learning how to increase NOI on a multifamily property is the single most important skill in this business, because NOI is what your building is actually worth. Anyone can fill in a spreadsheet. The money, though, is made in management and operations, and that money shows up as net operating income. During a recent coaching day with my clients, a W-2 couple who closed their first seven-unit, I walked them through the exact math behind forcing NOI up and turning it into a BRRRR cash-out refinance. This is that breakdown: the real multifamily deal math, not the guru version.
The multifamily money equation
Everything starts with one equation. Get this and you understand the whole game.
Step 1: Gross rental income
This is your total income from the building. For the sake of an example, say a building brings in $95,000 in gross rental income. That is the top line you build everything off of.
Step 2: Operating expenses (target 30 to 35 percent)
Operating expenses, or OpEx, are what it costs to run the property: taxes, utilities, cleaning, leasing, and repairs and maintenance. On a small building that is dialed in, OpEx should land around 30 percent of income, maybe up to 35 percent if you are running a little heavier. Controlling this ratio is one of the most direct levers you have to raise NOI.
Step 3: NOI equals income minus OpEx
Gross rental income minus operating expenses equals your NOI. That is it. Critically, NOI does not include your mortgage debt service, and it does not include one-time capital expenditures. Taxes and utilities absolutely go above the NOI line. Your principal and interest payment does not. If you blur that line, you will misread what your building is worth.
Step 4: Below the line is net cash flow
Below NOI sits your debt service (your principal and interest payment) and your CapEx. Subtract those from NOI and you get your net cash flow, which is your real cash return for the year. A good CPA should be able to prepare a net cash flow statement for you. Right now my clients are on an interest-only loan, which keeps that debt service lighter early on while they push NOI.
CapEx vs repairs, and why mixing them destroys your NOI
This trips up almost every new investor. A repair is a routine, day-to-day fix: replacing an outlet, fixing a garbage disposal. On a well-run seven-unit, you should not have many of those. A capital expenditure (CapEx) is something you only replace every few years, like a unit turn, carpet, appliances, or adding washers and dryers or storage. There is no fixed dollar threshold; the test is how often the item needs replacing. For more on this distinction, the IRS guidance on tangible property regulations covers how improvements differ from repairs.
Here is the trap: people take CapEx and pump it into their operating expenses. That artificially crushes their reported NOI. CapEx belongs below the NOI line, not inside OpEx. Misclassify it and you make a profitable building look weak, which directly lowers the value a lender or appraiser will assign.
How forcing NOI drives the BRRRR refinance
This is where the strategy clicks. Multifamily value is based on NOI. So when you force NOI up, by raising income and lowering expenses through light value-add and tight operations, you raise the appraised value of the building. A higher value lets you refinance and pull capital back out, then recycle that capital into the next deal. That is the engine of the multifamily BRRRR cash-out refinance.
One of my clients put his goal perfectly: get to a 25-unit, because that is roughly the scale where you can target a sizable cash-out refinance. Each building you buy is essentially another bank you can draw equity from later. But scale is a product of the systems underneath it, which is why running your first deal cleanly matters so much. I cover that operational foundation in managing your first small multifamily property.
Financing is not guaranteed, so do not over-commit to a deadline
Here is a real example from my own portfolio. I recently had a Fannie Mae loan approved at a high dollar amount and a low interest rate, and then the terms got cut hard, roughly $2 million less in proceeds, so I am now more likely moving to CMBS (commercial mortgage-backed securities) instead. The lesson is simple: refinance proceeds are never guaranteed. Do not lock yourself into a rigid twelve-month refinance deadline. If rates are still high at month twelve, you wait. If they drop later, you can borrow more, your debt service is lower, and your deal gets stronger. Be patient and let interest rates do their thing.
Report your NOI honestly, or you cannot refinance
This is one of the most important and least understood points. What you put on your tax return is how a lender calculates your NOI. You cannot write everything off to show a loss and avoid taxes, then walk into the bank and claim a high NOI to justify a big refinance. Lenders will look at your return, see you expensed everything as repairs and maintenance, and your value evaporates.
So for the years leading up to a refinance, you want the property to look as profitable as it honestly is, enough to comfortably hit a 1.2 debt service coverage ratio (DSCR). You can be more aggressive with write-offs after you refinance. Plan this timing deliberately with your CPA. For the metric itself, here is a plain explainer of the debt service coverage ratio, and a reference on what counts as a capital expenditure.
Why year one is often break-even
Put it all together and you can see why I tell clients year one is frequently close to break-even. You are intentionally spending on CapEx, unit turns and improvements, to drive NOI higher. That spending sits below the NOI line and reduces this year’s net cash flow. It is a deliberate trade: invest now to raise the building’s value, then capture the upside at refinance. Patience and disciplined operations, not luck, are what make the math work.
Run your own numbers
If you want to model all of this on a real deal, use the same tool I use to underwrite: the Multifamily Deal Analyzer. And if you want a deeper walkthrough of evaluating a building before you buy, read how to analyze multifamily properties for a profitable investment.
This article is educational and reflects one video plus my own experience. It is not financial, investment, legal, or tax advice, and it is not a guarantee of returns. Confirm all tax treatment with your own CPA and validate every assumption for your own deal before acting.
Frequently Asked Questions
What is NOI in multifamily real estate?
NOI, or net operating income, is your gross rental income minus operating expenses such as taxes, utilities, cleaning, leasing, and repairs and maintenance. It does not include your mortgage debt service or one-time CapEx. NOI is the number lenders and appraisers use to value the building, which is why protecting and growing it matters so much.
What percentage should operating expenses be on a small multifamily?
On a small building that is dialed in, operating expenses often run around 30 percent of gross income, and up to roughly 35 percent. They include taxes, utilities, cleaning, leasing, and repairs and maintenance. Keeping this ratio in check is one of the most direct ways to increase NOI and the value of the property.
What is the difference between CapEx and repairs?
A repair is a routine, day-to-day fix such as replacing an outlet or a garbage disposal. CapEx, or a capital expenditure, is something you replace only every few years, like a unit turn, carpet, or appliances. There is no fixed dollar threshold; the test is how often the item needs replacing. Mixing CapEx into operating expenses wrongly lowers your reported NOI.
How does increasing NOI help with a BRRRR cash-out refinance?
Multifamily value is based on NOI, so forcing NOI up through higher income and lower expenses raises the appraised value. A higher value lets you refinance and pull more capital back out of the deal. That recycled capital funds the next purchase, which is the core of the BRRRR strategy. Financing terms can still change, so never assume your proceeds are guaranteed.
Why is year one often break-even on a multifamily deal?
Year one is frequently break-even because you are spending heavily on CapEx, such as unit turns and improvements, to push NOI higher. That early spending sits below your NOI line and reduces net cash flow for the year. It is a deliberate trade: invest now to raise the value, then capture the upside at refinance.